What Prescription Drugs Does Medicare Cover? Here’s What to Check Before Open Enrollment
If you take prescription medications regularly, your Medicare drug coverage deserves a close look every year.
Why? Because the prescription coverage you have today may not look exactly the same next year.
Your medication could move to a different cost tier. Your copay could change. Your plan could change which pharmacies it considers preferred. A medication may have new coverage requirements. And in some cases, your plan's formulary—the list of covered prescription drugs—can change.
That's why Medicare prescription drug coverage should be one of the first things you review before Medicare Open Enrollment.
And you don't need to be a Medicare expert to do it. You just need to know what to look for.
What Is Medicare Prescription Drug Coverage?
Medicare prescription drug coverage is generally provided through Medicare Part D or through a Medicare Advantage plan that includes prescription drug coverage. Original Medicare by itself generally doesn't cover most prescription drugs you take at home.
People with Original Medicare can generally get prescription drug coverage through a separate Part D plan. Many Medicare Advantage plans, meanwhile, include prescription drug coverage as part of the plan.
The important thing is to understand how your current coverage works and what your plan will cover in the upcoming year.
Why Should You Review Your Prescription Coverage Every Year?
It's easy to think:
"My medications are covered now, so I'm good."
But Medicare plans can change their costs and coverage from year to year. That's why Medicare recommends reviewing your plan during the annual enrollment period. Your plan's information can tell you about changes to premiums, benefits, cost-sharing, and drug coverage for the upcoming year.
A medication that costs $5 today might cost more next year. Or perhaps nothing changes at all. The point is that you won't know until you look.
1. Make a List of Every Prescription You Take
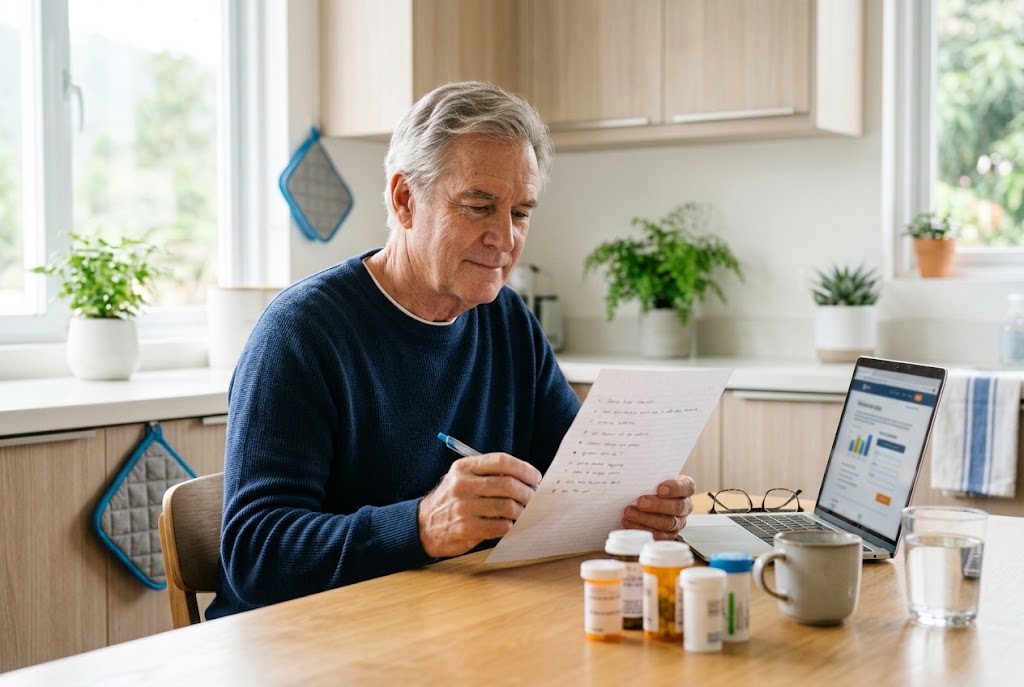
Before comparing Medicare drug plans, start with something simple. Make a list.
Write down:
Medication name
Dosage
How often you take it
How many prescriptions you typically fill each month
Preferred pharmacy
Don't rely on memory if you take several medications. If you're helping a parent or spouse review their Medicare coverage, ask them to gather all of their prescription information before you start comparing plans. This list becomes your starting point.
2. Check Your Plan's Formulary
Here's an insurance word worth knowing:
Formulary.
A formulary is essentially a list of prescription drugs covered by a Medicare drug plan. Different plans can cover different medications. That's why you shouldn't assume that because one Medicare plan covers your medication, every plan will cover it the same way.
When reviewing a plan, look up each medication on the plan's current formulary. If you're comparing plans, check your medications against each plan you're considering. Don't just look at the monthly premium.
3. Find Out Which Drug Tier Your Medication Is In
Medicare drug plans commonly organize medications into different tiers. The tier can affect how much you pay. For example, a plan might have:
Lower-cost generic drugs
Preferred brand-name drugs
Non-preferred drugs
Higher-cost specialty medications
The exact number and structure of tiers can vary by plan. So if your medication is covered, that's only the first question. The next question is:
"How much will I pay for it?"
4. Check Your Copay or Coinsurance
Your medication may be covered but still cost more than expected. Some prescriptions have a fixed copayment, while others may involve coinsurance, where you pay a percentage of the cost.
When reviewing your coverage, look at what you could actually pay when you pick up your medication. And don't forget to consider how often you refill it.
A small difference per prescription can become a meaningful annual expense if you're filling that prescription every month.
5. Check Whether Your Pharmacy Is Preferred
Here's another detail that can make a difference: Where you fill your prescriptions.
Some Medicare drug plans have pharmacies they consider preferred. Using a preferred pharmacy may result in lower out-of-pocket costs than using another participating pharmacy, depending on the plan. Before choosing a plan, check:
Is my current pharmacy in network?
Is it considered preferred?
Are there other preferred pharmacies nearby?
Does the plan offer mail-order options?
Would changing pharmacies actually save me money?
Your favorite pharmacy might be convenient—but it's worth seeing how it fits with your plan.
6. Look for Coverage Rules
Sometimes a medication is covered, but there are additional requirements.
You may see terms such as:
Prior Authorization
The plan may require approval before it covers certain medications.
Step Therapy
The plan may require you to try another medication first before covering a particular drug.
Quantity Limits
The plan may limit how much of a medication you can receive within a certain period. These rules don't necessarily mean a medication isn't covered. But they can affect how easily and how quickly you receive it.
7. Check Whether Your Medications Changed From Last Year
This is one of the biggest reasons to review your coverage. Your Medicare drug plan may change its formulary or cost-sharing structure for the upcoming year.
That could mean:
A medication is no longer covered
A medication moves to a different tier
Your cost changes
A different pharmacy becomes preferred
A coverage restriction is added or changed
Your plan's Annual Notice of Change can help you identify changes that take effect in the new plan year.
Read it carefully.
If something doesn't make sense, don't simply assume it's unimportant.
8. Don't Choose a Medicare Drug Plan Based Only on the Premium
This is a common mistake. Imagine two plans:
Plan A - Lower monthly premium
But your medications have higher copays.
Plan B - Higher monthly premium
But the prescriptions you take regularly cost less.
Which plan is cheaper? It depends. That's why the best plan isn't necessarily the one with the lowest monthly premium. You want to consider the overall cost of your medications and coverage.
Think about: Premium + prescription costs + other applicable out-of-pocket costs rather than looking at the premium alone.
What If You Take Generic Medications?
That's great—but you should still review your coverage. Generic medications are often less expensive than brand-name medications, but your actual cost can still depend on the plan's formulary, tier, pharmacy network, and other rules.
Don't assume:
"They're generic, so they're automatically cheap."
Check the actual cost under your plan.
What If Your Medication Isn't Covered?
Don't panic. If you discover that a medication isn't covered by a particular plan, that doesn't necessarily mean you're stuck. You may want to:
Check another Medicare drug plan
Ask your doctor whether an appropriate alternative exists
Ask whether an exception process may apply
Compare the total cost of another plan
However, don't stop taking a prescribed medication simply because you're reviewing your insurance. Talk with your healthcare provider about medication changes. Your health comes first.
What If Your Prescription Costs Are Getting Too High?
If your medication costs are becoming difficult to manage, Open Enrollment is a good time to investigate your options. But don't wait until January to discover that your prescriptions have become unaffordable. Start reviewing your medications now.
Ask:
What am I paying today?
What will I pay next year?
Are there lower-cost options available under another plan?
Does my current plan still make sense for the medications I take?
These questions can help you make a much more informed decision.
Medicare Prescription Drug Coverage and Open Enrollment
Medicare's Annual Enrollment Period runs from: October 15 through December 7. During this period, people with Medicare can make certain changes to their Medicare health and prescription drug coverage.
Changes generally take effect January 1, 2027. This makes October an excellent time to start gathering your prescription information rather than waiting until the last few weeks of enrollment.
Your Medicare Prescription Review Checklist
Before Open Enrollment, grab your medication list and check:
💊 Your medications
What prescriptions do I take?
What dosage do I take?
How often do I refill them?
📋 Coverage
Is each medication covered?
Is it on the plan's formulary?
Did its tier change?
Are there new coverage requirements?
💰 Costs
What is my copay?
Is there coinsurance?
What is the monthly premium?
What could I spend over the course of the year?
🏪 Pharmacy
Is my pharmacy in network?
Is it a preferred pharmacy?
Would mail order be useful?
Is another pharmacy less expensive?
📅 Next year
Did I receive my Annual Notice of Change?
What is changing January 1?
Does my current plan still make sense?
Don't Wait Until Your Prescription Is at the Pharmacy
One of the worst times to discover a coverage problem is when you're standing at the pharmacy counter. That's why an annual review is so valuable.
You can find out about changes before you need the medication. You can ask questions. You can compare your options. And you can make a decision based on information rather than surprises.
Frequently Asked Questions
Does Medicare cover prescription drugs?
Original Medicare generally doesn't cover most prescription drugs you take at home. Prescription drug coverage is generally available through a separate Medicare Part D plan or through a Medicare Advantage plan that includes drug coverage.
What is a Medicare formulary?
A formulary is a list of prescription medications covered by a Medicare drug plan. Plans can have different formularies and different cost-sharing rules.
Can my prescription coverage change each year?
Yes. Medicare drug plans can make changes to their costs, formularies, and coverage rules. Your plan's Annual Notice of Change explains important changes for the upcoming year.
Should I choose the Medicare plan with the lowest premium?
Not necessarily. Consider your premium alongside prescription costs, deductibles, copays, coinsurance, pharmacy networks, and other applicable out-of-pocket costs.
What is a preferred pharmacy?
A preferred pharmacy is a pharmacy that may offer lower out-of-pocket costs under a particular Medicare drug plan. The exact savings and network rules depend on the plan.
When can I change my Medicare prescription drug plan?
The Medicare Annual Enrollment Period generally runs from October 15 through December 7. Certain circumstances may also qualify someone for a Special Enrollment Period.
The Bottom Line
Prescription coverage is one of the most important parts of your Medicare plan if you take regular medications. Before Open Enrollment, don't just ask:
"What's my monthly premium?"
Ask:
"Are my medications covered?"
"How much will I pay?"
"Is my pharmacy preferred?"
"Did anything change?"
"Does this plan still make sense for me?"
Those questions can give you a much clearer picture of your Medicare prescription coverage for the year ahead. At We Know Life & Health, Dale Earp and Rachel Earp believe Medicare decisions should be based on understanding—not confusion or pressure. You don't have to know every Medicare term. You just need to know what questions to ask.
Ready to review your Medicare coverage?
Talk with We Know Life & Health and get help understanding your options before Open Enrollment.
You may also enjoy these related articles: What Should You Look for in Your Medicare Plan Before Open Enrollment?
Education first. Relationships always.